Amazon KDP Taxes Explained: Tax Forms, Withholding and Publishing Records
Amazon KDP taxes involve more than a year-end form. Learn how the KDP tax interview, W-9 and W-8 documentation, withholding, tax forms, payment records, and publishing expenses fit together.
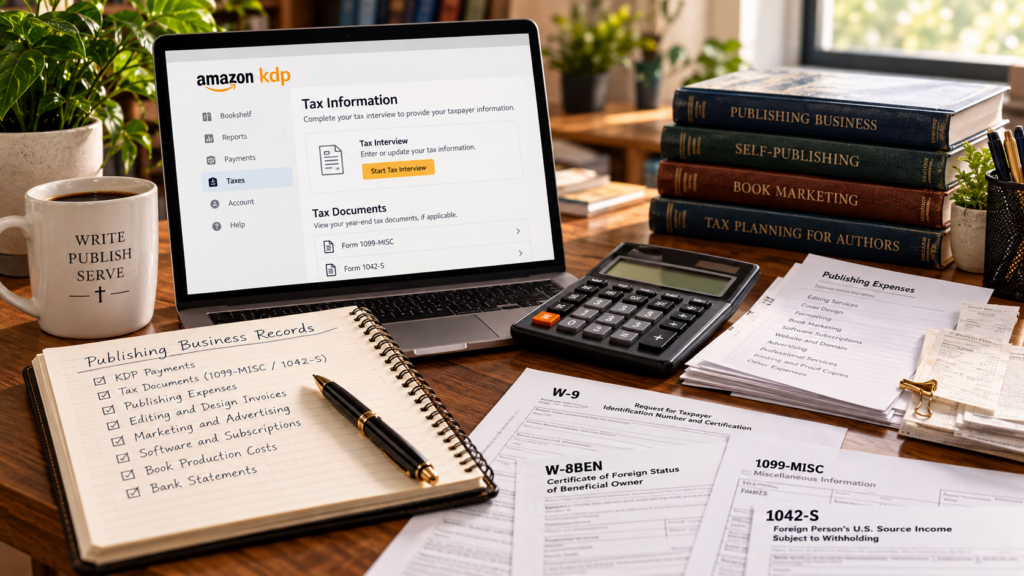
Publishing through Amazon KDP creates more than royalty income. It also creates tax documentation and recordkeeping responsibilities that publishers need to understand from the beginning.
KDP requires publishers to provide valid taxpayer information, and Amazon may issue tax documents based on the publisher’s tax status and payments received. For publishers outside the United States, U.S. withholding rules and tax treaties can add another layer of complexity.
The important distinction is that Amazon’s KDP tax system and your personal or business tax return are not the same thing. KDP collects information, applies withholding when required, and provides certain tax documents. How income and expenses ultimately appear on a tax return depends on the publisher’s circumstances and applicable tax law.
Understanding that system makes it easier to maintain good records, recognize the documents Amazon provides, and know when a tax question requires professional advice.
Why Amazon KDP Requires Tax Information
Amazon requires KDP publishers, including certain nonprofit and tax-exempt organizations, to provide taxpayer identification information.
This happens through the KDP tax interview.
The interview collects information Amazon needs to determine the appropriate U.S. tax documentation and whether payments may be subject to tax reporting or withholding.
For publishers, completing the interview accurately is important because incorrect information can create problems with tax documentation, withholding, or account status.
Your tax information should also be revisited when circumstances change. A change in legal name, country of residence, business structure, taxpayer identification number, or other relevant information may require the KDP tax interview to be completed again.
Tax setup should therefore be treated as part of maintaining a publishing account, not as a one-time box to check and forget.
Understanding the KDP Tax Interview
The KDP tax interview asks a series of questions designed to establish the publisher’s tax identity.
One of the most important distinctions is whether the publisher is considered a U.S. person or a non-U.S. person for U.S. tax purposes.
That determination affects the documentation Amazon collects.
U.S. publishers generally provide information associated with Form W-9.
Non-U.S. publishers generally provide the appropriate Form W-8 information. For many individual foreign publishers, this may involve Form W-8BEN, while businesses and other entities may require different documentation.
The correct form depends on the publisher’s legal and tax circumstances.
This is one reason publishers should resist copying another author’s tax setup. Two people publishing nearly identical books through KDP can have very different tax requirements because they live in different countries, operate through different business structures, or have different taxpayer classifications.
W-9 and W-8 Forms Serve Different Purposes
A W-9 is generally used to provide taxpayer information for a U.S. person.
The form identifies information such as the taxpayer’s legal name and taxpayer identification number. Amazon uses information collected through its tax interview to satisfy applicable U.S. tax reporting requirements.
W-8 forms serve a different purpose. They are generally used by non-U.S. persons to document foreign status and, when applicable, establish eligibility for benefits under an income tax treaty.
There is not one W-8 form appropriate for every foreign publisher.
For example, an individual author publishing personally may have different documentation requirements from a foreign corporation or partnership.
The safest publishing practice is straightforward: complete Amazon’s tax interview using accurate information about the person or entity that actually owns the KDP account and receives the publishing income.
What Tax Documents Can KDP Publishers Receive?
One weakness in many discussions of KDP taxes is that every type of online income gets grouped under the same “1099” label.
KDP has its own reporting procedures.
U.S. publishers who meet the applicable reporting requirements may receive Form 1099-MISC from Amazon for KDP payments.
Non-U.S. publishers may receive Form 1042-S, which reports certain U.S.-source income paid to foreign persons and related withholding information.
Amazon currently makes year-end KDP tax forms available through the publisher’s account and Amazon’s tax-document system. Timing differs by form.
A publisher should not assume that failing to receive a particular form means the income can be ignored.
Tax forms are reporting documents. They do not necessarily represent every piece of financial information a publisher needs to maintain.
Your own records remain important.
Why Your KDP Tax Form May Not Match Your Royalty Reports
This is a particularly important distinction for publishers.
KDP royalty reports track royalties earned.
Year-end tax documents generally reflect payments received during the applicable reporting year.
Those are not necessarily the same amounts.
KDP typically pays royalties approximately 60 days after the end of the month in which they were earned. As a result, royalties earned late in one calendar year may not be paid until the following year.
That timing difference can cause a publisher to compare a royalty report with a year-end tax form and conclude incorrectly that something is missing.
Good publishing records should therefore distinguish among:
Royalties earned
Payments received
Taxes withheld, when applicable
Publishing expenses
Keeping those categories separate makes year-end reconciliation considerably easier.
Tax Withholding for Non-U.S. Publishers
International publishing adds another dimension to KDP taxation.
A non-U.S. publisher receiving U.S.-source payments may be subject to U.S. withholding. The applicable rate depends on the publisher’s tax status and other factors.
Tax treaties between the United States and certain countries may reduce the withholding rate for qualifying publishers.
This is one reason accurate information in the KDP tax interview matters. Amazon uses the information provided to determine the withholding treatment that applies to payments under its system.
Publishers should not rely on a generic online list claiming that every author from a particular country receives a particular withholding rate. Treaty eligibility and tax status can involve details that a simple country chart cannot capture.
The KDP tax interview should provide information about the withholding rate Amazon determines from the information supplied.
When that result appears inconsistent with a publisher’s circumstances, obtaining qualified tax advice may be preferable to guessing at the correct treatment.
KDP Withholding Is Not the Same as Your Final Tax Liability
Another important distinction is between tax withheld from a payment and the amount of tax ultimately owed.
Withholding is money deducted from a payment under applicable tax rules.
Final tax liability is determined through the tax system that applies to the individual or business receiving the income.
The two amounts may not be identical.
For international publishers, matters can become more complicated because both U.S. tax rules and the tax rules of the publisher’s home country may need to be considered. Tax treaties and foreign tax credit systems may also become relevant.
Those issues extend beyond KDP account administration.
Christian Publishing Hub can explain how the publishing platform operates, but determining the tax treatment of a particular publisher’s income requires consideration of that publisher’s individual circumstances.
Publishing Income Requires Good Records
Tax documentation becomes much easier when financial records are maintained throughout the year instead of reconstructed at tax time.
For a publishing operation, useful records may include:
- KDP payment reports
- year-end tax documents
- bank records showing Amazon deposits
- invoices from editors, designers, illustrators, and other professionals
- receipts for software and publishing services
- advertising records
- printing and proof-copy expenses
- business-related subscription records
- invoices for website and marketing services
- records relating to equipment or other business assets
The goal is not simply to accumulate receipts.
A useful recordkeeping system should make it possible to identify where money came from, what an expenditure was for, when it occurred, and how it relates to the publishing activity.
Publishing Expenses Need Documentation
Publishing a professional book can involve substantial expenditures.
Editing, proofreading, cover design, illustration, formatting, advertising, software, professional services, and other costs may all be part of operating a publishing activity.
That does not mean every purchase associated loosely with writing automatically becomes a tax deduction.
For U.S. business tax purposes, deductible business expenses generally must satisfy applicable requirements, including rules concerning ordinary and necessary business expenses. Special rules can also apply to particular types of expenditures.
The practical lesson for publishers is not to decide tax treatment based on the name of an expense.
Instead, document the transaction.
For each significant publishing expense, retain information that establishes:
- who was paid
- what was purchased
- how much was paid
- when it was paid
- proof of payment
- the business purpose of the expense
An invoice saying “editorial services for Book Title” is considerably more useful than an unexplained charge appearing on a credit card statement months later.
Separate Business and Personal Activity When Practical
A dedicated business bank account is not a universal requirement for every individual publishing through KDP, but separating publishing transactions from personal spending can make recordkeeping substantially easier.
The same principle applies to credit cards, bookkeeping categories, invoices, receipts, and digital files.
A publisher operating several books, websites, advertising campaigns, or publishing imprints can quickly accumulate hundreds of transactions.
Clear separation helps answer basic questions:
How much did the publishing activity receive?
How much was spent?
Which book or publishing project generated an expense?
Which payments correspond to Amazon deposits?
Which expenses were personal rather than publishing-related?
That information is valuable not only for taxes but also for evaluating whether the publishing operation is financially sustainable.
Shared Expenses Require Careful Treatment
Some expenses may serve both personal and publishing purposes.
Internet service is an obvious example. A publisher may use the same connection for KDP administration, manuscript uploads, advertising, research, entertainment, personal email, and household activities.
Equipment, mobile phones, vehicles, and portions of a home can create similar questions.
There is no responsible universal percentage that every author should deduct.
Instead, the business use and applicable tax rules need to support whatever treatment is claimed.
This is an area where generic publishing advice often becomes unreliable. Statements such as “authors normally deduct 30% of their internet” may sound practical, but another author’s percentage does not establish yours.
Maintain records that support your own circumstances.
Home Office Rules Are More Specific Than Having a Writing Desk
Authors and publishers frequently hear that working from home automatically creates a home-office deduction.
It does not.
For U.S. taxpayers, the business use of a home is subject to specific requirements. Regular and exclusive business use can be important considerations, along with other applicable rules.
At the same time, the qualifying area does not necessarily have to be an entire separate room.
That distinction matters.
The relevant question is not whether someone owns a formal office with a door. It is whether the particular use of the space satisfies the applicable requirements.
Publishers considering a home-office deduction should evaluate the actual rules rather than relying on simplified author advice.
International Publishing Can Add Additional Tax Complexity
KDP allows a book to reach customers across numerous marketplaces, but international availability does not make the tax system uniform.
A publisher may encounter:
- U.S. withholding
- tax treaty questions
- foreign taxpayer identification requirements
- different tax documents
- currency differences
- home-country reporting requirements
- foreign tax rules
The significance of those issues depends on where the publisher resides, how the publishing business is structured, where income originates, and applicable tax law.
International publishers should therefore distinguish between two separate questions:
What information does Amazon require to administer my KDP account?
and
How does my country require me to report and pay tax on publishing income?
Amazon’s tax interview helps address the first question.
It does not replace professional guidance on the second.
Sales Tax and Income Tax Are Different
Sales tax and income tax are frequently confused in discussions about self-publishing.
They are fundamentally different.
Taxes associated with a customer’s retail purchase are not the same as taxes imposed on income received by the publisher.
Amazon, as a marketplace operator, handles many transaction-level tax obligations associated with sales made through its marketplaces. The publisher then receives royalties or other payments according to KDP’s applicable terms.
That does not mean Amazon assumes every possible tax responsibility connected with a publishing business.
A publisher selling books directly through a website, at events, through a separate business, or through other channels may encounter obligations that are outside the KDP system.
The important principle is to separate Amazon’s responsibilities as a marketplace from the publisher’s responsibilities as an individual or business.
Estimated Taxes May Apply to Publishing Income
Some publishers receiving income that is not subject to sufficient withholding may need to make estimated tax payments during the year.
For U.S. taxpayers, estimated tax is part of the pay-as-you-go federal tax system. Whether payments are required and how much should be paid depend on the taxpayer’s overall circumstances, including income, deductions, credits, withholding, and other taxes.
That is why simplistic rules such as “send 25% of your KDP income every quarter” should be avoided.
One publisher may have substantial withholding from another job. Another may operate publishing as a primary business. Another may have income from several businesses.
The appropriate calculation can differ considerably.
Publishers expecting meaningful taxable income should evaluate estimated-tax requirements based on their complete tax situation rather than an arbitrary percentage of KDP royalties.
How Long Should Publishers Keep Tax Records?
There is no single retention period appropriate for every publishing document.
The length of time records should be retained depends on what the record supports and the applicable period under tax law.
Some records relate to a particular year’s income or expenses. Others may establish the basis of an asset and need to be retained much longer. Employment-related records have their own requirements.
The more useful rule for a publisher is:
Keep records long enough to substantiate the income, expense, deduction, credit, asset, or other item they support.
Digital storage makes this easier than it once was.
Publishers can maintain organized folders by year and include KDP tax forms, payment reports, receipts, invoices, contracts, bank documentation, and other relevant financial records.
A Simple Year-Round Recordkeeping System for Publishers
A publishing business does not necessarily need complicated accounting software from its first sale.
What it does need is consistency.
A simple system can begin with four categories:
Income: Record payments received from KDP and other publishing channels.
Platform records: Retain KDP payment reports and year-end tax documents.
Expenses: Record publishing expenditures and preserve supporting invoices and receipts.
Business assets: Maintain separate records for significant equipment or other assets used in the publishing operation.
The system can be electronic or paper-based. What matters is that it clearly reflects income and expenses and preserves the documentation necessary to support the records.
As the publishing operation grows, bookkeeping software or professional accounting support may become worthwhile.
When Professional Tax Advice Makes Sense
There is no magic income level at which every publisher suddenly needs an accountant.
Complexity is usually the better indicator.
Professional tax guidance may become particularly valuable when a publisher has:
- significant income from multiple sources
- international withholding questions
- uncertainty about tax treaty treatment
- employees or contractors
- multiple business entities
- substantial publishing expenses
- significant equipment or other business assets
- direct sales in addition to marketplace sales
- complicated state or local tax questions
- uncertainty about estimated taxes
- uncertainty about how publishing income should be classified
The purpose of professional advice is not merely to find more deductions. It can also help a publisher establish sound systems before a problem develops.
Frequently Asked Questions
Does Amazon KDP require tax information?
Yes. KDP requires publishers to provide valid taxpayer information through its tax process. The documentation and withholding treatment depend in part on whether the publisher is considered a U.S. or non-U.S. person for U.S. tax purposes.
Does KDP issue a 1099-NEC?
KDP currently identifies Form 1099-MISC as the year-end tax form it issues to qualifying U.S. publishers. Other Amazon activities or unrelated businesses may use different information returns, which is one reason publishers should not assume every “1099” is interchangeable.
What tax form can a non-U.S. KDP publisher receive?
KDP may issue Form 1042-S to non-U.S. publishers when applicable. The form reports certain U.S.-source payments and withholding information.
Why doesn’t my KDP tax form match my royalty report?
KDP royalty reports can reflect when royalties were earned, while year-end tax reporting reflects payments received during the reporting year. Because KDP normally pays royalties after the month in which they are earned, the totals may not match.
Does receiving no tax form mean KDP income does not need to be reported?
Not necessarily. Tax-reporting obligations do not depend solely on whether a particular information form was received. Publishers should maintain complete income records and follow the tax rules that apply to their circumstances.
Can publishing expenses reduce taxable income?
Certain legitimate business expenses may be deductible when they satisfy the applicable tax requirements. Whether a particular expense qualifies and how it should be treated depends on the circumstances. Publishers should retain documentation supporting business expenditures.
Should I form an LLC because I publish through KDP?
Publishing through KDP does not by itself determine whether an LLC or another business structure is appropriate. Liability, administration, state law, taxation, ownership, and the publisher’s broader business circumstances can all affect that decision.
Does Amazon handle all of a publisher’s taxes?
No. Amazon handles particular tax-reporting, withholding, and marketplace responsibilities associated with its platform. Publishers can have additional federal, state, local, or international tax responsibilities depending on their circumstances and other sales channels.
Conclusion
Amazon KDP taxes are easier to understand when the platform’s responsibilities and the publisher’s responsibilities are separated.
KDP collects taxpayer information, determines applicable platform withholding, provides certain year-end tax documents, and maintains payment records. Publishers are responsible for keeping accurate business records and addressing the tax obligations that apply to their own publishing activities.
For a growing Christian publishing operation, good financial administration is part of responsible stewardship.
That means documenting income, preserving invoices and receipts, reconciling KDP payments, keeping tax information current, and recognizing when a question has moved beyond platform administration and into professional tax advice.
The objective is not to become a tax expert simply because you publish books.
It is to build a publishing operation with records strong enough to understand where the money came from, where it went, and what information is available when tax time arrives.